Banking Software Development Cost in 2026: Price, Compliance and Build vs Buy
Banking software development cost in 2026 by product type, what compliance adds (KYC, PCI DSS, DORA) and a build, buy or partner table to pick a path.
Your bank or fintech has a product idea, and the first vendor call ended with a number that made everyone go quiet. The next quote came back three times lower, so which one is real? This guide explains banking software development cost in 2026 by product type. It also shows what compliance adds and when to build, buy or partner.
Key takeaways
- At CodesClue, a banking prototype or internal tool runs about $8K to $25K. A mid-size product costs $25K to $70K, and a regulated customer platform starts from $70K.
- Published market ranges for a full mobile banking app run from about $40K for a basic MVP to $1M or more.
- Integrations with your core system and the compliance work move the price more than the number of screens.
- Most teams should not rebuild a core banking system. An API layer around the core usually costs less and carries less risk.
- Budget for life after launch: identity checks per user, audits, hosting and yearly maintenance.
How much does banking software development cost in 2026?
Banking software development cost usually starts at $8K to $25K for a prototype or an internal tool. A mid-size product, such as a customer portal on top of your existing core, runs $25K to $70K. A regulated customer-facing app or lending platform starts from $70K. These are CodesClue’s project ranges.
Other guides quote higher numbers because most of them price a full consumer banking app. Leanware lists $40K to $70K for a basic MVP and $100K to $250K for a mid-tier app. Innovecs puts a basic app at $40K to $90K. DashDevs starts its MVP band at $80K and runs a multi-market platform past $1M.
Why such a wide spread? Each vendor prices a different product, team location and level of compliance. A back-office dashboard and a neobank are both “banking software”, but they share very little. Treat every range, ours included, as a starting point until someone reads your brief.
Banking software development cost by product type
The product you build sets the base of your bill. Find the row closest to your idea.
| Product type | Examples | What drives the cost | Typical CodesClue tier |
|---|---|---|---|
| Internal tool or dashboard | Operations dashboard, reporting tool, case management for the compliance team | Data sources, user roles, reports | $8K to $25K, more with many modules |
| Customer portal on your core | Online banking front end, business banking portal, document upload | Core integration, login security, account views | $25K to $70K |
| Mobile banking app | Balances, transfers, card controls, alerts | Two platforms, biometrics, payments, app store rules | From $70K |
| Lending platform | Loan origination, credit decisions, repayment schedules | Credit data providers, decision rules, document checks | From $70K |
| Payments or wallet platform | Transfers, merchant payments, reconciliation | Payment providers, real-time ledgers, fraud checks | $25K to $70K for one flow, from $70K for more |
| Core banking replacement | New ledger, accounts and products engine | Data migration, parallel running, regulator sign-off | From $70K, often far more |
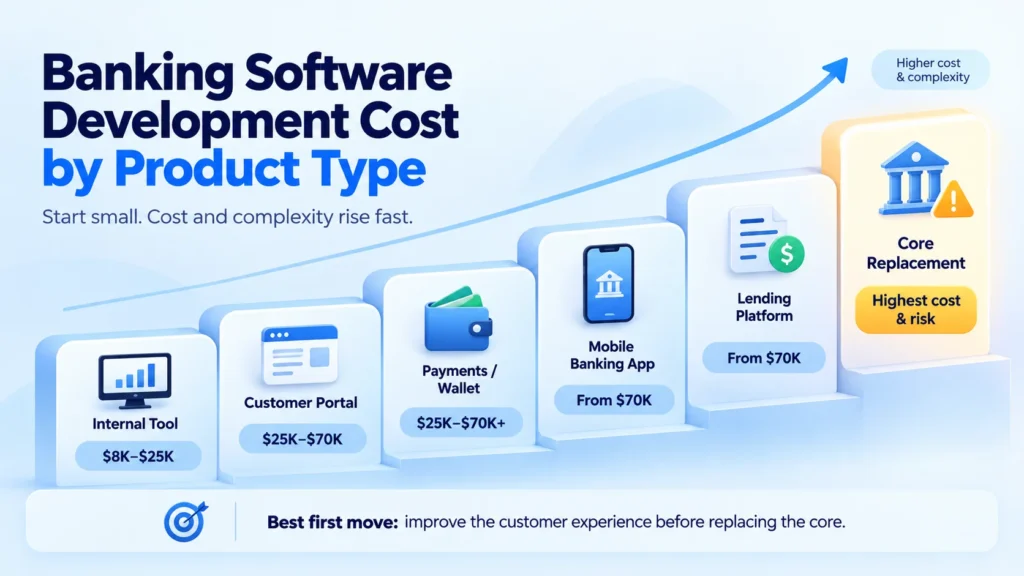
Notice the last row. Replacing a core system is the most expensive and riskiest choice on the list. Most teams get more value from something smaller first.
Building for a fintech rather than a bank? Our fintech software development page covers payments, lending and wallet products.
What drives the price of banking software?
Five things decide most of the budget. Screens matter less than people expect.
- Integrations. Every link to your core system, card processor, identity provider or credit bureau needs its own work and its own tests.
- Compliance and security. Audit logs, access roles, encryption and screening checks add real hours to every feature.
- The back office. Staff need screens to review cases, approve limits and fix errors. Teams often forget this half of the product.
- Money movement. Real-time balances and reconciliation take careful design, because a rounding error here becomes a customer complaint.
- Platforms. Web only costs less than web plus iOS plus Android.
Pro tip: Ask every vendor to price integrations as separate lines. If one quote hides them inside “development”, you cannot compare it with the others.
The compliance part of the bill
Compliance is not one fee. It shows up inside the build, in the tools you pay for, and in the checks you run before launch. The rules depend on where you operate and what you do with money and card data.
| Market | Rules you will hear about | What it usually adds to the build |
|---|---|---|
| United States | GLBA and the FTC Safeguards Rule, FFIEC guidance for banks, SOC 2 reports that bank partners often ask for | Written security program, access controls, encryption, vendor reviews |
| European Union | DORA (opens in a new tab) (applies from 17 January 2025), PSD2 strong customer authentication, GDPR | Incident reporting, resilience testing, two-factor login for payments, data rights |
| United Kingdom | FCA rules, Consumer Duty, UK GDPR | Clear customer journeys, complaint records, data rights |
| Anywhere you touch card data | PCI DSS (opens in a new tab), now at version 4.0.1 | Network rules, scans and audits for any system that stores or sees card numbers |
Inside the software, the same few features cover most of these rules.
Identity checks at onboarding, sanctions and politically exposed person (PEP) screening, transaction monitoring, audit logs and role-based access appear in almost every project. We build them into the flow, so each check runs the same way every time and leaves a record. Our post on HIPAA and PCI DSS compliance explains the card data rules in more depth.
Pro tip: Keep card numbers out of your own systems. A payment provider that stores cards for you and hands back a token can shrink your PCI DSS scope, your audit cost and your risk.
One honest limit: we are engineers, not your lawyers. Your compliance officer or legal adviser decides which rules apply. We turn those decisions into software and records your auditors can read.
Build, buy or partner: which option fits you?
Not every banking idea needs a custom build. Start with the simplest path that still fits your plan.
| Your situation | Best fit | Why |
|---|---|---|
| Your process is standard, like a basic savings account | Buy a vendor product | Someone already solved it and keeps it compliant |
| You are a fintech without a banking licence | Partner with a bank or Banking as a Service (BaaS) provider, then build your own app on top | The partner holds the licence and the accounts |
| Your core works, but customers want a better app or portal | Build a custom front end on an API layer around the core | You improve the experience without touching the ledger |
| Your workflow is your edge, like a niche lending model | Build custom | No product fits, and copying a rival’s tool gives you no advantage |
| Your core truly blocks every new product | Modernize in stages | A big-bang replacement puts every account at risk on one day |
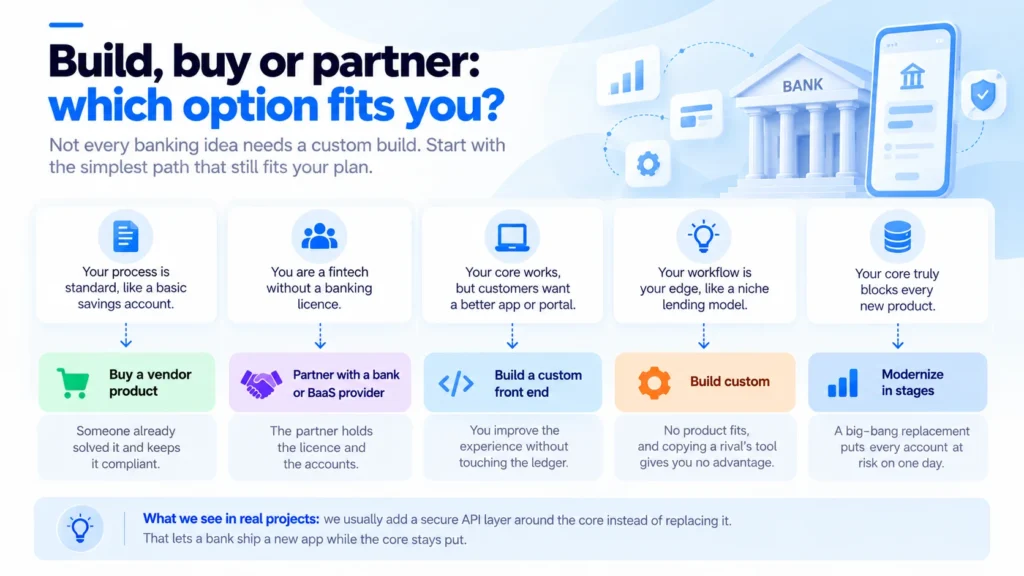
What we see in real projects: we usually add a secure API layer around the core instead of replacing it. That lets a bank ship a new app while the core stays put. Our legacy software modernization guide explains the staged path in more detail.
When would we tell you not to build? If a licensed vendor already covers 90% of your process, pay for it and spend your budget on the part that makes you different.
Want a second opinion on your quote or your scope? Send us your brief and we will tell you which path we would take.
A real example: the EmberPay payments platform
EmberPay is a web platform for fast, secure payments with real-time tracking and reconciliation. CodesClue designed and built it with Angular and MySQL.
The product has five core modules: payments, transactions, accounts, alerts and reports. One dashboard covers the whole payment lifecycle, from the moment a payment starts to the moment it reconciles.
The lesson for your budget sits in that list. Only one module is the payment itself. The other four exist so staff can see, check and explain every movement of money. Plan your budget around that back-office work, not only the customer screens. You can read the full EmberPay case study to see how it works.
How to estimate your banking software budget in 6 steps
- Name the one job. Write one sentence on what the first release must do, for example “let business customers upload documents and see loan status”.
- List every user type. Customers, branch staff, compliance officers and admins each need their own screens and rules.
- List every system it touches. Core banking, card processor, identity checks, credit data, email and SMS.
- Ask your compliance team for the rule list. Get it in writing before any vendor quotes.
- Split launch from later. Move anything that is not needed on day one into a second phase.
- Add running costs. Count hosting, per-check fees from identity providers, audits and yearly maintenance.
Pro tip: Pay for a short discovery phase before the full build. A few weeks of scoping often removes features nobody needs and finds the integration that would have blown the budget later.
Checklist before you ask for quotes
- One-sentence goal for the first release
- User types and what each one can do
- Systems to connect, with any API documents you have
- Markets you will serve and the rules your compliance team named
- Whether you will store, see or never touch card data
- Web, iOS, Android, or a mix
- Your launch date and anything driving it
- Who will own the code, the hosting and the support after launch
Send the same pack to every vendor. Our guide on how to choose a custom software development company includes a scorecard to compare their answers.
Running costs after launch
The build is only the first bill. Banking software keeps costing money while it runs.
- Identity and screening checks. Most providers charge per check, so this grows with every new customer.
- Hosting and monitoring. Expect higher spend than a normal web app, because you need backups, logs and alerts you can show an auditor.
- Audits and penetration tests. Plan for at least one independent security test before launch and then on a regular schedule.
- Maintenance. Leanware and Cleveroad both estimate about 15% to 20% of the build cost each year.
If you need extra engineers after launch, a dedicated team is often simpler than hiring. With CodesClue, development starts within 48 hours once your requirements are discussed and the developer is approved. Our guide on how to hire dedicated developers covers that model.
Common mistakes to avoid
- Pricing only the customer app. The staff tools and reports often take as much work as the screens customers see.
- Starting with a core replacement. Fix the experience first through an API layer, then replace parts of the core one at a time.
- Leaving compliance to the end. Audit logs and access roles cost far more to add later than to design in from the start.
- Storing card data you do not need. Every system that sees card numbers joins your PCI DSS audit.
- Comparing quotes with different scopes. A low number often means a missing integration, not a better team.
- Forgetting per-check fees. Identity checks look small per user and large at 50,000 users.
Pro tip: Ask each vendor to show you a past audit log or admin screen from a finance project. It tells you more about their compliance habits than any slide.
Get a clear banking software development cost for your project
You now know what drives banking software development cost, what compliance adds and when to build, buy or partner. Share your one-sentence goal and the systems you need to connect, and we will send a written estimate with milestones. See our banking software development services or talk to an engineer to start.
FAQs
How much does it cost to build a banking app in 2026?
A basic banking app with balances, transfers and alerts usually starts around $40K in published market ranges, and a full multi-market platform can pass $1M. At CodesClue, a regulated customer-facing app starts from $70K. The final number depends on platforms, integrations with your core system and the rules in your markets.
How long does banking software development take?
It depends on the product type, the number of systems you connect and the reviews your compliance team needs. Integrations, security testing and compliance sign-off often take longer than the screens. A small first release shortens the path to launch. Ask every vendor for a milestone plan with the estimate, so you can compare timelines line by line.
How much does compliance add to banking software cost?
There is no fixed share, because it depends on your markets and whether you touch card data. Compliance work sits inside many features: identity checks, screening, audit logs, access roles and encryption. Add outside costs on top, such as penetration tests, audits and per-check fees from identity providers. Ask vendors to list these lines separately.
Should a bank replace its core banking system?
Usually not as a first step. A full replacement means migrating every account and running two systems side by side, which is costly and risky. Most banks get faster results with an API layer around the core and new apps on top. They then replace parts of the core in stages.
Can a fintech launch without its own banking licence?
Yes, many do. A fintech can partner with a licensed bank or a Banking as a Service (BaaS) provider that holds the licence and the customer accounts. The fintech then builds its own app and back office on top. Your legal adviser should confirm the right setup for each market before you sign.
What is the lowest-risk way to start?
Start with the smallest release that proves your idea, such as one flow for one customer type in one market. Use a licensed partner for accounts, a payment provider that stores card data for you, and proven identity check services. That keeps your build and audit scope small while you learn what customers use.